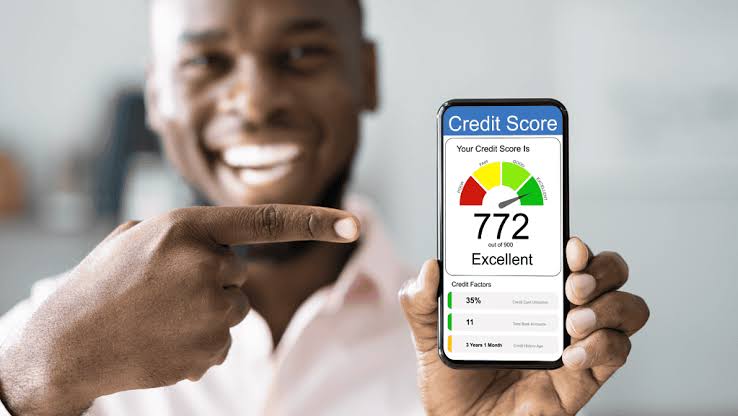
A credit score is a numerical assessment based on information in a person’s credit history. Financial institutions may use credit information when evaluating applications for loans, credit cards and other financial products.
However, there is an important point that is often overlooked: there is no single credit-scoring system used everywhere in the world. Scoring models, credit reporting systems and the information used by lenders can vary between countries and institutions.
What Information Can Affect a Credit Score?
Depending on the scoring system, factors may include payment history, outstanding debt, how much available credit is being used, the age of credit accounts, new credit applications and the types of credit accounts held.
In the United States, for example, FICO scores use five major categories: payment history, amounts owed, length of credit history, new credit and credit mix. :contentReference[oaicite:3]{index=3}
Why Paying on Time Matters
Payment history is an important part of many credit-scoring systems. Consistently missing payments can signal higher risk to lenders.
In the FICO model, payment history represents 35% of the score, making it the largest of the five main categories. :contentReference[oaicite:4]{index=4}
Credit Utilization
Credit utilization describes how much of your available revolving credit you are using. A person who regularly uses a large proportion of their available credit may appear more financially stretched to some scoring models.
For FICO scores, amounts owed account for 30% of the score and include factors such as total debt and credit utilization. :contentReference[oaicite:5]{index=5}
Why You May Have More Than One Credit Score
You may see different scores even when checking your credit information around the same time.
This can happen because different scoring models can use different formulas, different lenders may use different versions and credit information can vary between reporting sources.
The CFPB specifically notes that consumers do not necessarily have just one credit score and that scores can differ depending on the scoring model, data source and calculation date. :contentReference[oaicite:6]{index=6}
How to Build Better Credit Habits
- Pay credit obligations on time.
- Avoid taking on debt you cannot comfortably repay.
- Monitor your credit information when the service is available in your country.
- Avoid making unnecessary credit applications.
- Keep track of outstanding balances and payment dates.
Credit Scores Are Not the Whole Financial Picture
A credit score is only one part of a lending decision. Financial institutions may also consider income, existing debts, employment, collateral, the type of credit requested and other information.
Therefore, having a strong credit score does not guarantee approval for every financial product.
Final Takeaway
Credit scores are designed to help lenders estimate credit risk, but the system varies considerably between countries and scoring models. Understanding your local credit-reporting system, paying obligations on time and managing debt responsibly are more useful than focusing on a single number.